Why an ALTA Title Survey Matters Before Refinancing a Multi-Tenant Commercial Property
The survey sitting in your closing binder from the last loan may be seven or eight years old. Since then, tenants have come and gone, a pad site may have been built out, and the parking lot might have been restriped twice. A new lender won’t assume that old drawing still reflects the property. An ALTA title survey gives the lender and title company a current, detailed picture of the site, so start planning for it as soon as you decide to refinance.
What Lenders Need to Verify Before Refinancing
Lenders rely on it because it ties the physical site to the legal records. The survey is usually certified to the lender, the title company, and the borrower.
On a refinance, the lender wants to confirm that the property still matches what they’re lending against. They’re looking for things like encroachments, blocked access, buildings over easements, and changes to the site since the last loan. They also want to know the property has legal access to a public road. Any of these issues can affect the loan terms or the title policy.
Requirements can vary a lot by lender, loan type, and title company. Some lenders want a brand-new survey, while others may accept an updated or recertified version of a recent one. Ask your lender for their survey requirements and any Table A items in writing before you hire a surveyor.
Understanding Table A Items
Table A is a list of optional items that can be added to an ALTA survey. Examples include building dimensions, parking space counts, utility locations, and flood zone information. The lender or title company usually decides which items to include. Choosing the right list up front prevents costly revisions later.
Mapping Tenant Spaces, Access, and Shared Site Features
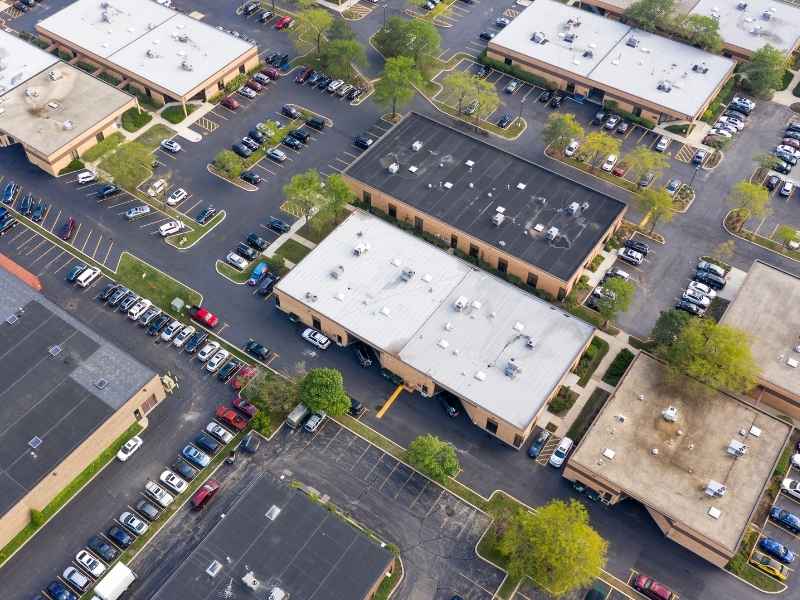
Multi-tenant properties are more complicated than single-tenant sites. A shopping center, office park, or mixed-use building may have several tenant suites, outparcels, shared drives, and common parking areas. Each of those features can affect how the property operates and how it’s valued. The survey needs to show them clearly.
Access is often the biggest concern. The surveyor will show curb cuts, driveways, and any cross-access easements that let customers move between parcels. If a key entrance crosses a neighbor’s land, the lender will want to see a recorded agreement that allows it. Without one, that access could be at risk.
Shared features deserve the same attention. Common areas, loading zones, dumpster enclosures, and detention ponds may serve more than one tenant or even more than one owner. Parking counts may also matter if leases or zoning rules require a set number of spaces. If your lender asks for a parking count, make sure it’s listed in the Table A items.
Identifying Changes Made Since the Previous Financing
Commercial sites change more than owners realize. A tenant may have added a drive-thru lane, a patio, or a new sign. A back parking area might have been expanded, or a storage building added near the rear line. These updates may never have been checked against the boundaries or recorded easements.
A new ALTA survey captures the site as it exists today. The surveyor will compare current conditions with the lot lines and plotted easements, and available property records. If a new improvement crosses a line or sits on an easement, the survey will show it. That gives you time to address it before the lender sees it as a surprise.
Make a list of every change you know about before the field crew arrives. Include tenant build-outs, paving work, new utility lines, and anything built by a neighbor near your line. Sharing old surveys, site plans, and permit drawings can also help the surveyor work faster.
Comparing the Survey With Current Title Documents
The ALTA survey and the title commitment are designed to work together. The title commitment is the title company’s report on ownership and recorded matters affecting the property. Schedule B of that commitment lists exceptions, such as easements, covenants, and agreements. The surveyor reviews these items and shows them on the drawing when their location can be mapped.
This review is where many issues come to light. An old utility easement might run under a newer building. A recorded access agreement might describe a driveway that no longer exists. The legal description in the deed might not match the one in the title commitment.
Give your surveyor the current title commitment and copies of the recorded documents as early as possible. The survey can’t be finalized properly without them. If the commitment changes after the survey is drafted, the surveyor may need to update the drawing.
Resolving Survey Issues Before the Refinance Closing
Survey issues don’t always stop a refinance, but they need attention. Once the draft survey is ready, your lender, title company, and attorney will review it. They may ask questions about encroachments, access, or easement conflicts. Answering those questions early keeps the closing date realistic.
Solutions depend on the problem. Some issues can be handled with a recorded easement, a boundary line agreement, or an estoppel from a neighbor. Others may be accepted by the lender with a specific exception in the title policy. Your attorney can advise you on which path fits your situation.
Build extra time into your schedule for this stage. Field work and drafting can take a few weeks on larger sites, and review comments can add more. If your rate lock or loan deadline depends on the survey, tell your surveyor about it on the first call.
Frequently Asked Questions
What is an ALTA title survey?
An ALTA title survey is a detailed commercial property survey prepared under national ALTA/NSPS standards. It shows boundaries, buildings, access, easements, and other site conditions. Lenders and title companies use it to evaluate risk before closing a loan. It’s often required for commercial purchases and refinances.
Can I reuse my old ALTA survey for a refinance?
Sometimes, but it depends on the lender and title company. Some will accept an updated or recertified survey if the site hasn’t changed much. Others require a completely new survey for every loan. Ask your lender early so you know which option to plan for.
How long does an ALTA survey take for a multi-tenant property?
Many ALTA surveys take a few weeks, and larger sites may take longer. The timeline depends on the property size, the number of Table A items, and how quickly title documents arrive. Review comments from the lender or title company can add extra time. Order the survey as soon as your refinance is underway.